🔹 1. Kemexel Ecommerce Pvt. Ltd. vs Sales Tax Officer (Delhi High Court, 2025)
📌 Key Issue:
Whether the department can issue a Section 73 notice again after accepting the scrutiny reply
🧾 Judgment:
- Court held: Once a reply is accepted under Section 61, no further action can be taken
- The Section 73 notice was quashed
💡 Principle:
👉 Double proceedings are not allowed
👉 The department cannot reopen the same issue after closure
📚 Source:
🔹 2. Patanjali Ayurved Ltd. vs Union of India (Allahabad High Court, 2025)
📌 Key Issue:
Whether Section 74 proceedings cancel the Section 122 penalty
🧾 Judgment:
- Court held:
- Section 73/74 proceedings are independent
- Penalty under Section 122 can still apply
💡 Principle:
👉 Multiple proceedings under the GST law can run independently
📚 Source:
🔹 3. Basavaraj V. Sajjan vs DGGI (Karnataka High Court, 2025)
📌 Key Issue:
Wrong application of Section 74 (fraud not proven)
🧾 Judgment:
- Court converted:
- Section 74 → Section 73
- Reason:
- No fraud or suppression was proved
💡 Principle:
👉 Wrong classification by the department can be corrected by the courts
👉 Fraud must be clearly established
📚 Source:
🔴 4. S.A. Iron & Alloys Pvt. Ltd. Case (Allahabad High Court, 2025)
📌 Key Issue:
Can Section 74 be applied without proof of fraud?
🧾 Judgment:
- Court held:
- Section 74 cannot be invoked without clear findings of fraud
- The order was quashed, and a refund was allowed
💡 Principle:
👉 Fraud must be specifically proved
👉 Arbitrary use of Section 74 is invalid
📚 Source:
🔹 5. Madras High Court – Natural Justice Case (2024–25)
📌 Key Issue:
The order was passed without a proper hearing under Section 74
🧾 Judgment:
- Order set aside because:
- The taxpayer was not given a proper opportunity
💡 Principle:
👉 Natural justice is mandatory
👉 Hearing opportunity is compulsory before demand
📚 Source:
🔴 6. Allahabad High Court – Goods Movement Case (2025)
📌 Key Issue:
Section 74 invoked despite actual movement of goods
🧾 Judgment:
- Court held:
- If goods movement is proven → Section 74 not valid
💡 Principle:
👉 Genuine transactions cannot be treated as fraud
📚 Source:
🔹 7. Composite SCN & Multiple Years Cases (Various HCs + Supreme Court Trend)
📌 Key Issue:
Whether one notice can cover multiple years under Section 74
🧾 Judgment Trend:
- Courts + Supreme Court allow:
- Consolidated notices in fraud cases
💡 Principle:
👉 In fraud cases, the department can issue a single SCN for multiple periods
📚 Source:
🔹 8. General HC Principles on GST SCN Validity
Important rulings across High Courts:
- SCN without proper details → invalid
- Order before hearing date → invalid
- Same issue repeated → not allowed
📚 Source:
⚖️ Key Legal Principles (Very Important for Blog)
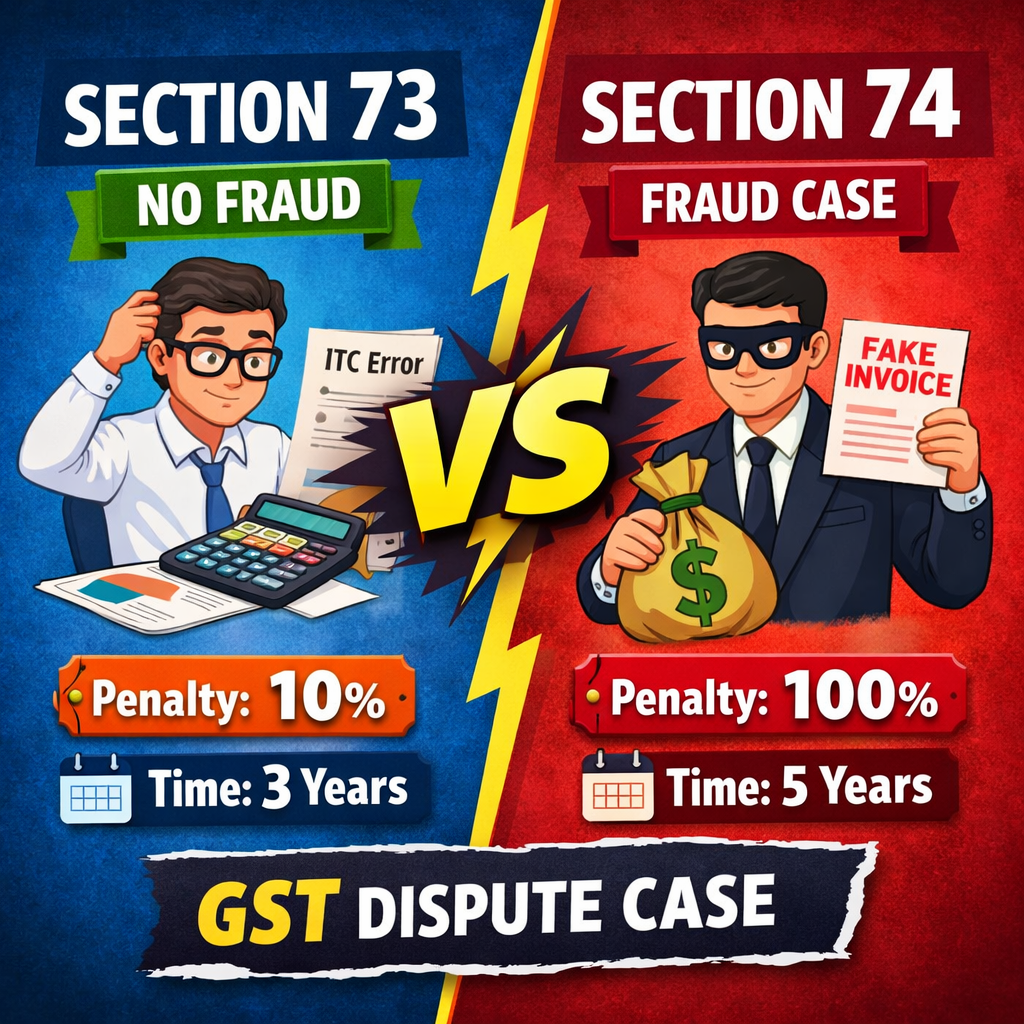
🧠 1. Fraud is Mandatory for Section 74
- Cannot be assumed
- Must be proved with evidence
🧠 2. Natural Justice Rule
- SCN + Proper Hearing = Mandatory
- Otherwise order invalid
🧠 3. Reclassification Allowed
- Section 74 → Section 73 possible
- If the fraud is not proven
🧠 4. No Double Jeopardy
- The same issue cannot be reopened
- Once accepted → closed
🧠 5. Independent Proceedings
- Section 73/74 ≠ Section 122 penalty
📊 Practical Blog Insight
👉 Most notices initially issued under Section 74 (strict)
👉 Later reduced to Section 73 (relief) after litigation
👉 Courts are protecting genuine taxpayers from misuse
🔥 Suggested Blog Section
“What Courts Say About GST Notices”
- The department cannot misuse Section 74
- Fraud must be proven
- Proper hearing is mandatory
- Genuine mistakes → Section 73 only