
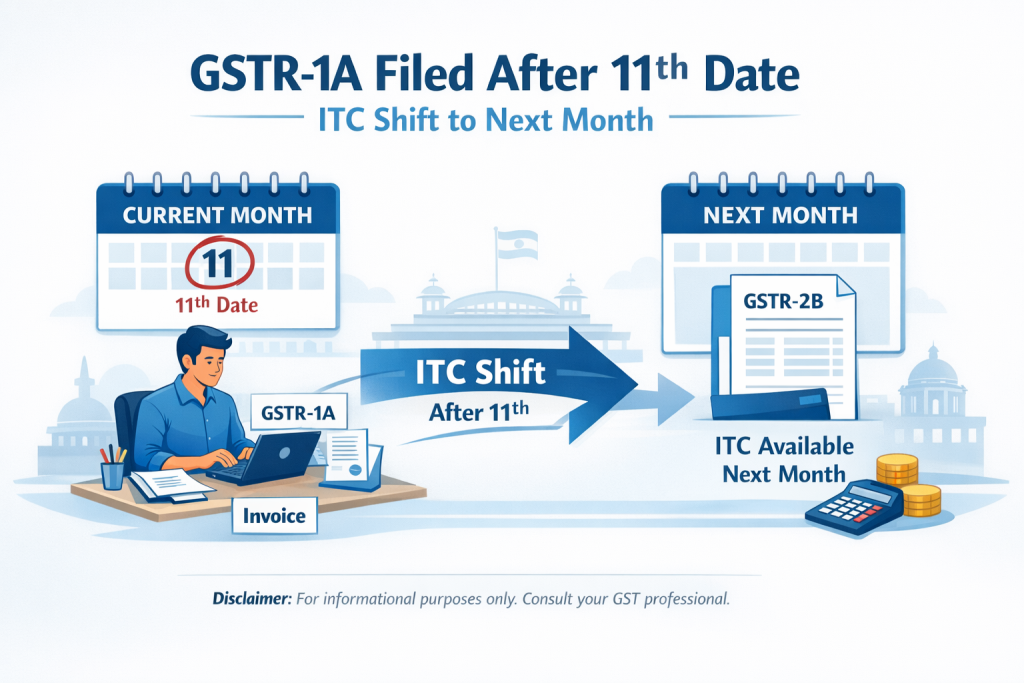
GSTR-1A Filed After 11th/ 13th Date: Can the Receiver Claim ITC? Complete Guide with Examples
Introduction
Many taxpayers are confused about Input Tax Credit (ITC) eligibility when a supplier files or amends invoices through GSTR-1A after the 11th or 13th of the month.
A common question is:
If GSTR-1A is filed after the 11th date, will the receiver lose ITC?
The answer is NO, but there is a timing impact.
Let’s understand this clearly with practical examples.
What is GSTR-1A?
GSTR-1A is a form that allows the supplier to:
- Accept, reject, or amend invoices
- Based on recipient-side data visible in GSTR-2B / IFF
Any change made through GSTR-1A directly affects ITC visibility for the recipient.
Why is the 11th Date Important in GST?
The 11th of every month is the cut-off date for generating GSTR-2B.
| Filing Time | ITC Impact |
|---|---|
| Before 11th | Invoice appears in same month GSTR-2B |
| After 11th | Invoice shifts to next month GSTR-2B |
Can ITC Be Claimed If GSTR-1A Is Filed After 11th?
✅ YES — but in the next month
- ITC is not lost
- ITC is only deferred
- Receiver can claim ITC only when invoice appears in GSTR-2B
Legal Basis
As per Rule 36(4) of CGST Rules:
ITC can be availed only for invoices reflected in GSTR-2B
So:
- Invoice not in 2B → ❌ ITC not allowed
- Invoice appears later → ✅ ITC allowed later
Practical Example (Very Important)
Example 1: Amendment After 11th
| Particular | Details |
|---|---|
| Invoice Date | 5 April 2025 |
| GSTR-1A Filed | 15 May 2025 |
| 11th Date | Already crossed |
| Appears in GSTR-2B | June 2025 |
| ITC Claim Allowed | June GSTR-3B or later |
✔ ITC safe
✔ No penalty to receiver
✔ Only timing difference
Example 2: Filed Before 11th
| Invoice Filed | 8 May |
| Appears in 2B | May |
| ITC Claim | May GSTR-3B |
What Receiver Cannot Do
- ❌ Cannot claim ITC based on invoice copy
- ❌ Cannot manually adjust ITC
- ❌ Cannot claim ITC if invoice not in 2B
Best Practices for Businesses
✔ Follow up with suppliers before 10th
✔ Monthly 2B reconciliation
✔ Claim ITC only from 2B
✔ Keep email proof of follow-ups
FAQs
Q1. Will ITC lapse if supplier files late?
No, ITC does not lapse. It will appear in later GSTR-2B.
Q2. Can ITC be claimed in next financial year?
Yes, subject to Section 16(4) time limit.
Q3. Is GSTR-1A mandatory?
It is optional, but amendments affect ITC timing.
Conclusion
If GSTR-1A is filed after the 11th date, ITC is not lost.
It will reflect in the next month’s GSTR-2B and can be claimed then.
Understanding this helps businesses avoid wrong ITC claims and notices.
GSTR-1A ITC claim, ITC after 11th date, GST 2B ITC rules, delayed GSTR-1A impact, Rule 36(4) ITC
Disclaimer
The information provided in this article is for general informational and educational purposes only and should not be considered as legal, tax, or professional advice.
GST laws, rules, and interpretations are subject to frequent changes and departmental clarifications. Readers are advised to consult their GST consultant, Chartered Accountant, or tax professional before taking any action based on this content.
The author and publisher shall not be responsible for any loss, penalty, or consequences arising from reliance on the information provided herein.